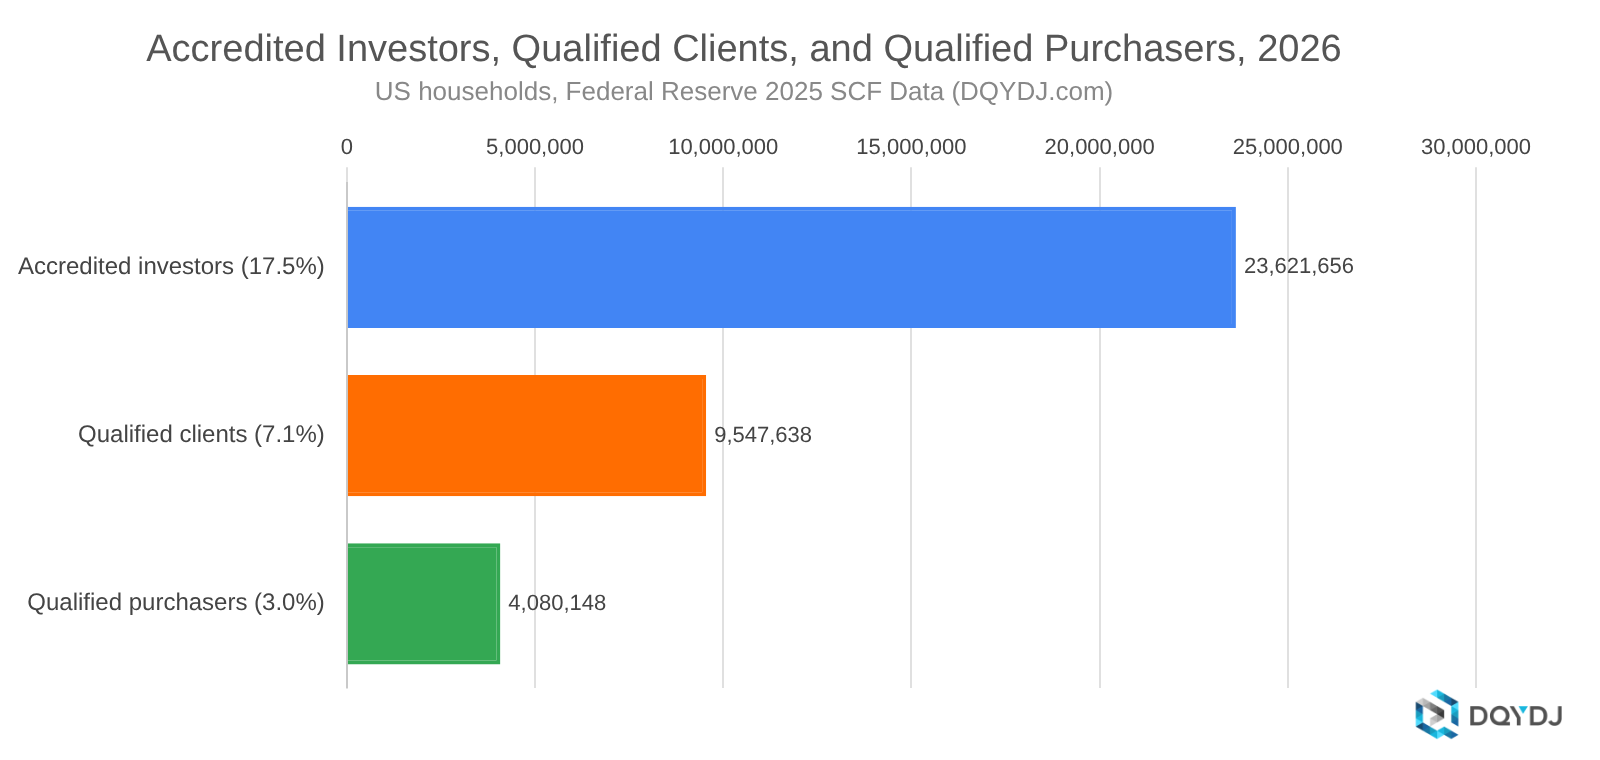
I estimate 4,080,148 households in the United States, or 3.0% of households, were qualified purchasers in 2026. By my estimates, that's 17.3% as many households as accredited investors and 42.7% as many households as qualified clients.
Qualified purchasers held roughly $76.3 trillion in total wealth in 2026. According to estimates from the 2025 Federal Reserve SCF, released in October 2026, that's around 45.9% of all privately held household wealth. Most interviews took place in 2025, with ~1/7 in early 2026. It's the latest data until roughly late 2029.
What is a qualified purchaser?
Qualified purchasers are a special class of investors mentioned in the (amended) Investment Company Act of 1940 and fully clarified by the Securities and Exchange Commission in 1997. The simplest way to qualify is by holding $5,000,000 in investments.
Funds with only qualified purchasers can avoid SEC registration rules until they hit 2,000 investors. Without qualified purchasers, this rule caps limited partners at 100, effectively limiting total fund size. This fund size bonus is on top of performance fees allowed for qualified clients and private investment participation (in general) for accredited investors.
TinySeed wrote an excellent article on the SEC accredited investor cap and its interplay with qualified purchasers.
Qualified purchaser criteria
In 1997, the SEC clarified what counts as an investment for a qualified purchaser otherwise defined in U.S. Code § 80a–2(a)(51). The most common way to qualify is to maintain $5,000,000 in investments (net of any borrowing to acquire those investments) – but there are a few angles to qualify:
- If you own $5,000,000 or more in investments alone or with a spouse
- If you have a closely held family company that controls $5,000,000 or more in investments
- If you have a trust which wasn't formed to meet the qualified purchaser criteria for this particular investment and controls $5,000,000 or more in investments
- If you invest $25,000,000 or more at your own discretion, for yourself or for other qualified purchasers
You'll note that the qualified purchaser criteria revolves around investments, not net worth ex-primary home equity, as with accredited investors and qualified clients.
What qualifies as an investment for qualified purchasers?
If you read through the SEC's rulemaking release from 1997, you'll see that they attempted to narrow assets down into those that require investment intent with some element of navigating a market. In short – and stated a few ways in various supporting documentation – they tried to define a "sophisticated investor".
Here's what counts as an "investment" for a potential qualified purchaser:
- Publicly traded securities
- Financial contracts entered into for investment purposes
- Equity in private companies you don't control (including via investment vehicles, even if the vehicle has some active control over smaller firms, e.g., board seats)
- Equity in a private company you control if the company has $50 million or more in total shareholder equity
- Real estate held for investment purposes
- Commodity interests – including physical commodities such as gold – held for investment purposes
- Cash held for investment purposes, including bank deposits and CDs
- The cash surrender value of insurance policies
- Investments in an IRA or similar retirement account that you direct
You'll note some relatively common assets are missing here. Vacation homes, real estate you own used by your extended family, real estate you own for your business, jewelry, and antiques are out. Equity in small businesses you control – even if the company is worth $49 million! – is out. Commodity hedging you do for business purposes (or physical commodities you need to hold) is out.
Qualified purchaser estimate methodology
As you can see, unlike with the net worth tests for accredited investors and qualified clients, it's quite a lift to come up with an estimate for purchasers.
You'll find the backing documentation for the next section in these SCF documents:
Estimating qualified purchasers
I start with financial assets ("fin"), then add net equity in non-residential real estate ("nnresre") and non-actively managed business equity ("nonactbus"). Next, subtract other miscellaneous financial assets ("othfin") – don't worry, I'll selectively add some types back! – and other debt ("odebt") – margin loans and loans against retirement plans and life insurance. I don't remove miscellaneous debt, which isn't tied to investments.
Then I make a few judgment calls. Here are bullets, quoting the rule I'm leaning on where applicable:
- Rentals count, vacation homes – even rented – don't. The rule counts "Real estate held for investment purposes," but not property used "for personal purposes or as a place of business" ((b)(2), (c)(1)). I add the family's share of equity in residential properties that brought in income in 2024. Vacation and seasonal homes stay out even if rented – I treat them as personal use. This is a tough one: the survey lumps "other additional homes" in, we surely lose a few real rentals here, too.
- Real estate notes count. Land contracts and mortgages the family is carrying on property it sold are investments.
- Checking accounts and prepaid cards don't. Cash only counts if "held for investment purposes" ((b)(7)). I keep savings, money market accounts, and CDs, and treat checking as spending money. Yes, I know, plenty of people stage investment cash in checking... including yours truly! It's a judgment call, and it doesn't move the numbers too much.
- Retirement accounts and cash value life insurance count. The rule allows investments in "an individual retirement account or similar account" the person directs ((g)(4)), so I drop workplace plans where the owner says they have no choice in how it's invested. It also counts "the net cash surrender value of an insurance policy" ((b)(7)(ii)). I leave annuities in, too.
- Some "other" assets are added back: other metals, miscellaneous real estate, oil/gas/mineral leases, and crypto. Technically, the 1997 rule predates crypto as an asset class (okay, hit me with your eCash and Hashcash jokes, I'll smile). I leave out gold and silver here – the public data lumps them in with silverware.
- Businesses the family actively manages only count if the company is worth $50 million or more. The rule excludes securities of a company the investor controls unless it has "shareholders' equity of not less than $50 million" ((b)(1)). I estimate company size from the value of the family's share and the percent they own (market value here, not book equity).
Finally, I filter the resulting variable for $5 million or more, and 💥... you've got your qualified purchaser subset. Treat it as a household proxy: the rule only counts a spouse's investments in some cases (and never an unmarried partner's).
On control. Let's talk about control for a second... Federal law presumes owning more than 25% of a company's voting securities is control (see 15 U.S.C. § 80a-2(a)(9)). If you count actively managed stakes of 25% or less, you'd add back about 18,000 households.
Again, these are estimates and I'm doing my best with the ambiguity, here. Run your assumptions yourself if you disagree with my inclusions. I made judgment calls – for example, excluding not-otherwise-classifiable cash (read: possibly held at home!) – but it should be a defensible set.
Funds of qualified purchasers
Qualified purchasers are a huge advantage to a fund because their participation makes it easier to raise large funds without edging into higher disclosure requirements.
Consider the common fund structure of 2-and-20 – that's a 2 percent annual management fee plus 20% carried interest over some hurdle. Raising a $25,000,000 fund – $500,000 in fees charged for fund activities and employment annually – generally means you're looking at $250,000 minimum commitment sizes. That's a heavy lift from most accredited investors who aren't qualified purchasers – at a relatively modest fund size.
One possible compromise? As mentioned in TinySeed's post, a separate fund (or sleeve) of qualified purchasers can invest in parallel with a fund of traditional investors. This allows larger effective funds and bigger check sizes out of the joint "fund". Of course, it's an administrative burden... so larger funds will generally continue to limit entry to qualified purchasers unless and until the rules change.
(And no, it's not entirely regulation's fault – qualified purchasers should be better able to handle Bernie Madoff-type blow-up fraud situations than other accredited investors.)
Had fun reading the statistics? Read some of our posts on investing and net worth:
- Net Worth by Year in the United States
- Income Percentile by Age in the United States
- Household Income Percentile in the United States
- ETF Return Calculator
For past versions of this post, see here:
