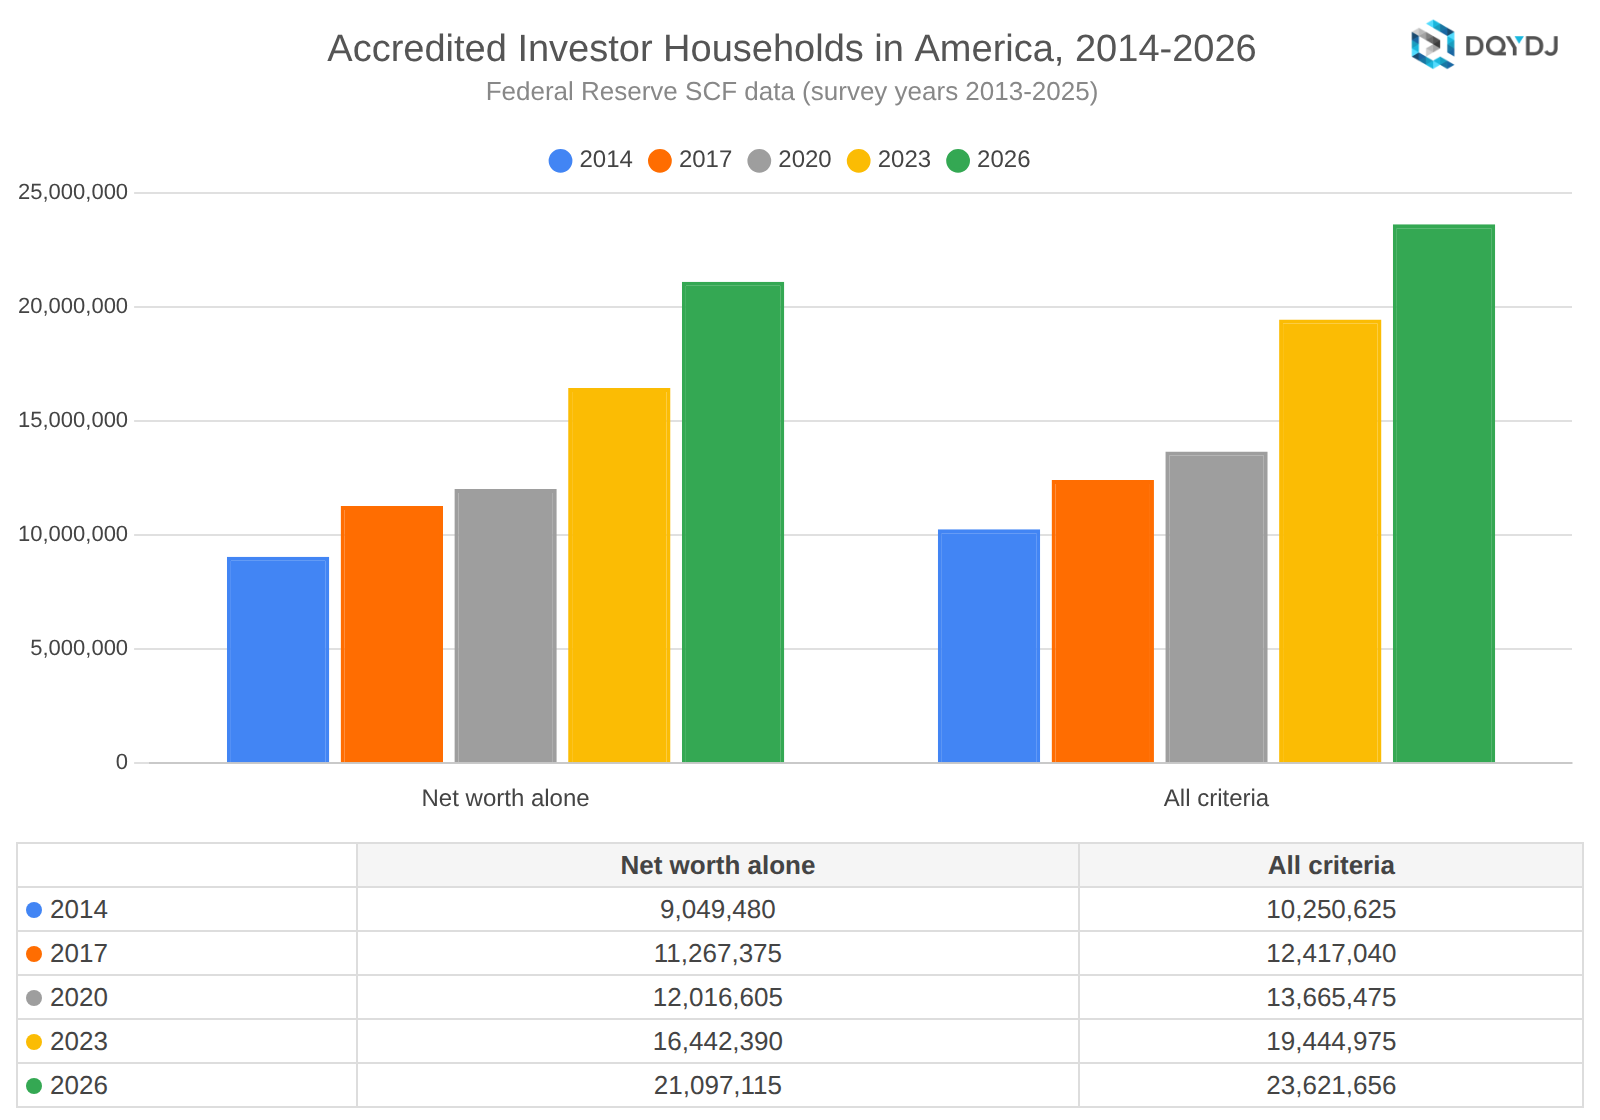
We estimate in 2026 there were 23,621,656 accredited investor households in America. Roughly 17.5% of American households qualified as accredited investors.
Those households controlled roughly $135.7 trillion in wealth in 2026. Measured by the SCF, that was around 81.6% of all private wealth in America.
(Note these estimates don't include professional certifications allowing accreditation. More discussion below.)
Accredited investors in the United States: more than 1 in 6 households
In the Federal Reserve's 2025 SCF – with about one-seventh of interviews conducted in early 2026 – roughly 17.5% of households qualify as accredited investors. (See our net worth data, here).
In 2023, I estimated 14.8% of households were accredited investors. In the three years between surveys, roughly an additional 4,176,700 households qualified – a 21.5% increase, though I improved my methodology some this year (discussion below). Looking for a headline? There are now more than double the number of accredited investor households versus my estimates from the 2013 SCF.
Further, accredited investor households controlled roughly $109.5 trillion in wealth in 2023 (2022 SCF data). The pool of accredited investor wealth increased 24% in 3 years (about 13% after inflation).
| 2014 | 2017 | 2020 | 2023 | 2026 | |
| Accredited: Net Worth Alone | 9,049,480 | 11,267,375 | 12,016,605 | 16,442,390 | 21,097,115 |
| Accredited: All Criteria | 10,250,625 | 12,417,040 | 13,665,475 | 19,444,975 | 23,621,656 |
| Total Households | 122,530,070 | 125,981,700 | 128,642,430 | 131,306,390 | 134,963,691 |
What are the criteria in the United States to be an accredited investor?
The Securities Act of 1933, §230.501, defines the terms and definitions to be an Accredited Investor. The three most common ways of accreditation for an individual/household are the following:
- More than $1,000,000 in net worth outside equity in a primary residence (see our Net Worth Percentile Calculator, which allows primary home equity removal)
- (or) An individual earning more than $200,000 in each of the last two years and expecting it to continue in the current year.
- (or) With a spouse or spousal equivalent, earning more than $300,000 jointly in each of the last two years and expecting it to continue in the current year.
Note that the original law specifically calls out net worth for the classification. It notably disallows equity in a primary residence – an amendment from 2011.
And net worth is the most common way to qualify: around 21.1 million households would have qualified on just the net worth criteria (89.3% of accredited households). See our post on millionaires in America.
Other ways to qualify: professional licenses
Since 2020, there's been a fourth path for individuals that doesn't care about net worth or income. The SEC added this criterion:
Any natural person holding in good standing one or more professional certifications or designations or credentials from an accredited educational institution that the Commission has designated as qualifying an individual for accredited investor status.
Right now, the list is: General Securities Representative (Series 7), Investment Adviser Representative (Series 65), and Private Securities Offerings Representative (Series 82) licenses (here's the SEC order). The 2020 update let "spousal equivalents" – unmarried partners – combine income and net worth like spouses. It also added "knowledgeable employees" of private funds as accredited investors.
And the list may grow! On October 5, 2026 – right before we went to press on this series – the SEC asked for public comments on adding the CFA charter, the CFP certification, the CPA license, the Series 79, 86, and 87 licenses, and passing an accredited investor exam from FINRA.
It's not possible to estimate how many people qualify only through a credential – at least using the public microdata from the 2025 SCF.
Accredited investor methodology
All data for this post is from the Federal Reserve 2025 SCF microdata, released in October 2026. If you've seen our net worth brackets in America post, you'll know the general math from this survey.
However, for this post we add:
- Net worth MINUS primary home equity > $1,000,000 (or)
- If the house is underwater, I don't remove the debt because the rule states: debt "in excess of the estimated fair market value of the primary residence… shall be included as a liability."
- Household Income > $300,000 and Normal Income > $300,000 (or)
- No spouse or partner, Household Income > $200,000 and Normal Income > $200,000 (or)
- Either of
- Reference Person Income > $200,000 AND Normal Income > ($200,000 + Spouse Income)
- Spouse Income > $200,000 AND Normal Income > ($200,000 + Reference Person Income)
Splitting income between spouses
I had to derive "spouse" and "reference person" (previously "household head") or "no spouse or partner" income, as you can see. Here's the codebook for 2025, and here are the questions I'm using to split – pay on the main job, money taken out of their own business, pay from other jobs, Social Security, pension benefits, and IRA withdrawals (the survey records whose each one is):
- Reference person: x4112 + x4131 + x4509 + x5306 + pensions where x5315/x5323/x5331/x5415 = 1 + x6558
- Spouse: x4712 + x4731 + x5109 + x5311 + pensions where x5315/x5323/x5331/x5415 = 2 + x6566
New this edition: income is annualized by the respondent's chosen pay period. The survey asks for an amount and asks "And that amount is per…?". For the non-annual answer-ers (is that a word?), I annualize the number using the frequency questions (x4113, x4132, x4510 and x4713, x4732, x5110).
Earlier editions summed raw dollar amounts – most of the qualified PEUs were already quoting annual income. The change barely moves the total.
Single households need $200,000
Also new: single households ("No spouse or partner") only need $200,000 from all income sources. The $300,000 test is for couples. Here's the rule:
Any natural person who had an individual income in excess of $200,000 in each of the two most recent years or joint income with that person's spouse or spousal equivalent in excess of $300,000 in each of those years and has a reasonable expectation of reaching the same income level in the current year;
I better summed income sources this edition: earlier editions held singles to $300,000 unless their job earnings cleared $200,000; now singles qualify on $200,000 of all income. Think: wages, business, investments, etc. The change adds ~306,000 households.
Oh no, more exceptions
Of course, a lot of my methodology here is a good faith estimate. And whatever income test you choose is a proxy either way, so feel free to rerun the numbers yourself. The SEC asks for income over the threshold in each of the two most recent years, plus a reasonable expectation of clearing it again this year – the survey doesn't exactly answer that.
The income test also breaks for married couples making between $200,000 and $300,000 when one spouse's income is mostly investments, rentals, or other non-job income. Since the public survey data doesn't say who earned that income, neither spouse may clear $200,000 on paper. And household income can include money earned by other family members living there, like an adult child.
However – exceptions aren't too common, and I'm pretty happy with the math here. It's an excellent screen, and net worth is the bulk of the weight, regardless.
For comparison, SEC staff estimated 24.3 million accredited households from the 2022 survey. They counted household income toward the individual test, noting it is an upper bound.
Accredited investors: it's not everything in investing
Even knowing the exact number of people who qualify as accredited investors really doesn't tell you everything. Nor does it imply you should load up on the risk if you qualify. It merely means that a certain population clears the benchmark of one law (and the rules that followed) – the SEC thinks they either can lose enough or know enough about investing to fully realize the risks.
Accredited status doesn't always mean a person can invest. Sometimes the supply just isn't there for the investments that people would like to buy into. You'll still need to find opportunities, talk your way in, and sometimes clear other asset or income hurdles imposed by an investment. Additionally, many funds charge performance fees – for carried interest or promote you need to be a qualified client, not an accredited investor. Further, some funds require you to be a qualified purchaser, which uncaps the number of investments they can take from limited partners. In this post, I discuss the three designations.
And, finally - just because an investment is hard to buy into doesn't mean it's a good investment. Stories abound of athletes, musicians, lottery winners and other high net worth individuals who lose it all in private investments. When in doubt, do as we suggest elsewhere on the site - stick with an index fund.
Previous editions:
